

- Movable assets set to unlock financing
- Reforms aim to deepen financial inclusion
- New registry to unlock access to credit
BY MBONGENI NDLELA
MBABANE – The Central Bank of Eswatini is advancing plans that could transform financial inclusion in the country through the establishment of eight cooperative banks, a move expected to broaden access to financial services, stimulate entrepreneurship and unlock economic opportunities for thousands of emaSwati.
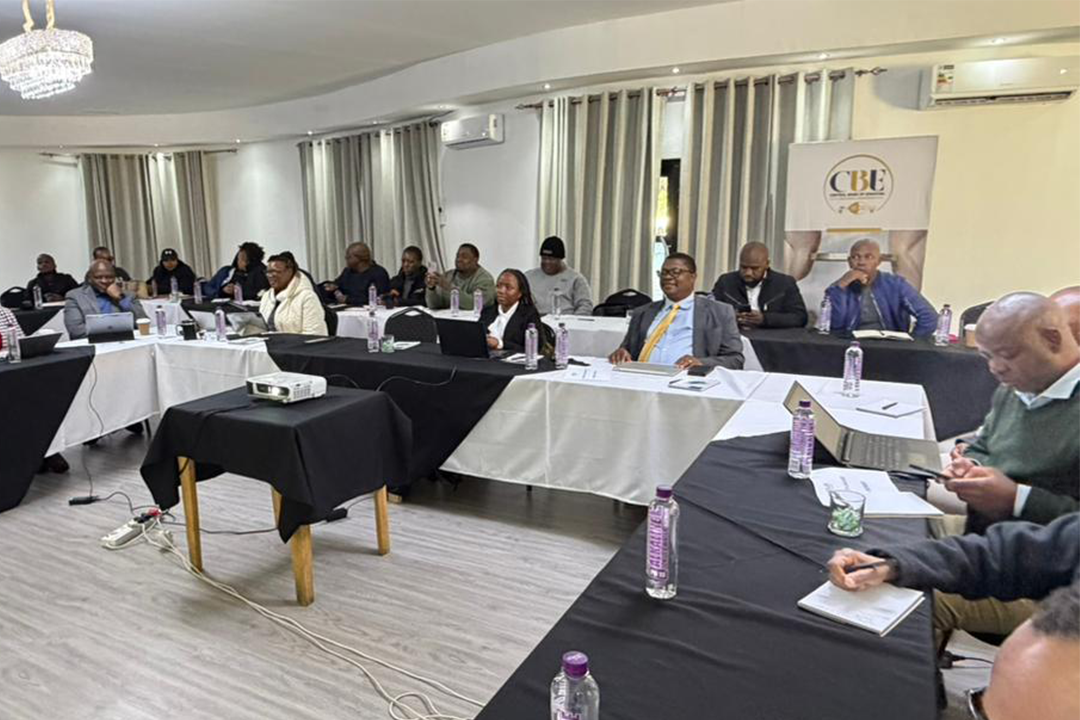
Governor Dr. Phil Mnisi announced the initiative during the Governor’s Annual Media Engagement Session held at Sibebe Resort, where he outlined several reforms aimed at deepening financial inclusion and expanding access to credit.
According to the Governor, the Central Bank has already conducted extensive research and benchmarking exercises to guide the development of the cooperative banking framework.
“In support of Government cooperative banking initiatives, the bank conducted a benchmarking study and developed a strategic policy note,” he said.
Dr. Mnisi explained that the policy note evaluates the regulatory landscape governing savings and credit cooperative societies and provides a roadmap for their possible transition into licensed banking institutions.
“This initiative is designed to deepen financial inclusion, drive economic development and foster sustainable business growth,” he said.
The Governor revealed that the Central Bank is actively working towards establishing a framework that would allow the licensing of eight cooperative banks in Eswatini.
“In that regard, the bank is working towards establishing a framework for licensing eight cooperative banks in Eswatini, drawing lessons from international best practices to make this vision a reality,” he said.
The announcement forms part of broader efforts to modernise the financial sector and ensure that underserved communities, small businesses and entrepreneurs have greater access to affordable financial services.
Dr. Mnisi said concerns have been raised about whether Eswatini risks becoming overbanked, given the number of financial institutions entering the market. However, he assured the public that the Central Bank carefully assesses every licence application to ensure it addresses a specific market need.
“We are not just issuing similar licences. We are looking at the type of licence and whether it addresses a specific niche,” he explained.
He cited the example of a recently approved digital banking licence aimed specifically at serving small and medium enterprises, as well as micro-enterprises.
“The licence is very narrowly defined, looking at the SME and micro space,” he said.
Similarly, building societies that transition into commercial banks are expected to expand beyond property financing and offer a wider range of financial products.
“Whenever we are looking at this, we ask whether it addresses a niche and whether it will accelerate the economy,” said the Governor.
In addition to cooperative banking reforms, Dr. Mnisi highlighted another important initiative currently under development — the Movable Collateral Registry.
The proposed registry will allow individuals and businesses to use movable assets such as vehicles, machinery, inventory and equipment as collateral when seeking financing.
“Once fully established, the registry will enable individuals and businesses to use movable assets as collateral when seeking financing from financial institutions,” he said.
Although still in its early stages, the Governor described the registry as a potentially game-changing reform that could unlock access to credit for many people who do not own land or buildings.
“While it represents an important reform with the potential to deepen financial inclusion and broaden access to credit, significant groundwork still needs to be undertaken before it can become operational,” he explained.
Dr. Mnisi said these reforms demonstrate the Central Bank’s commitment to building a more inclusive financial system capable of supporting entrepreneurship, investment and sustainable economic growth.
If successfully implemented, the cooperative banking programme and movable collateral registry could significantly expand economic participation and create new opportunities for businesses and communities across Eswatini.


