
….. Central Bank reports E29 billion money supply, E23.5 billion private sector credit and higher interest rates
BY MBONGENI NDLELA
MBABANE– Eswatini’s foreign reserves have climbed to E10.8 billion, while the country’s broad money supply has reached E29 billion, according to the latest figures released by the Central Bank of Eswatini (CBE).
The figures, contained in the Bank’s August/September 2026 Monthly Statistical Release, provide an important picture of the country’s financial position, showing improvements in foreign reserves, domestic liquidity and money supply, alongside a decline in monthly lending to the private sector.
The report also confirms that borrowing became more expensive in September after the Central Bank increased its discount rate by 25 basis points to 7.0 per cent, with the prime lending rate rising to 10.50 per cent.
For businesses, investors and ordinary emaSwati, the figures present a mixed picture of the economy, with stronger financial buffers and increased liquidity accompanied by higher borrowing costs.
One of the major developments reported by the Central Bank is the growth in gross official reserves, which reached E10.8 billion in September 2026.
The provisional figure represents an increase of 2.6 per cent compared with August and a 0.6 per cent improvement over the corresponding period in 2025.
Foreign reserves are financial assets held by the Central Bank to support the country’s external payment obligations and monetary arrangements.
They are particularly important for Eswatini because the country imports a substantial range of goods, including fuel, machinery, industrial equipment and consumer products.
The availability of foreign reserves helps the country meet international payment obligations and provides a financial buffer against external economic pressures.
According to the Central Bank, the country’s import cover improved from 2.4 months in August to 2.5 months in September.
This means the reserves were equivalent to approximately two and a half months of imports at the prevailing level of import expenditure.
Although the improvement is positive, the import cover figure remains below the commonly referenced international benchmark of three months, indicating that the country’s external financial position still requires careful management.
The increase in reserves is nevertheless an important development, particularly for a small, import-dependent economy operating within the Common Monetary Area.
PRIVATE SECTOR CREDIT REACHES E23.5 BILLION
Another major figure emerging from the Central Bank’s report is the E23.5 billion in credit extended to the private sector during August 2026.
The amount represents an increase of 10.5 per cent compared with August 2025, suggesting that the overall stock of credit available to households and businesses remained substantially higher than a year earlier.
However, the same figures reveal that private sector credit declined by 1.4 per cent between July and August.
This monthly contraction is an important development because lending plays a significant role in business activity, investment and household spending.
Private sector credit includes loans and other forms of financing extended by financial institutions to businesses and individuals.
For businesses, such financing can support the purchase of machinery, expansion of operations, acquisition of commercial property and the financing of working capital.
For households, credit can provide funding for housing, vehicles and other financial needs.
The annual growth of 10.5 per cent indicates that the outstanding amount of private sector credit was higher than in the previous year.
However, the monthly decline suggests that the stock of outstanding credit contracted during August.
The statistical release does not explain the specific reasons for this decline, and the figures alone cannot establish whether it resulted from reduced borrowing demand, loan repayments or changes in lending conditions.
Nevertheless, the development deserves attention because access to credit is closely linked to the ability of businesses to finance their operations and undertake new investments.
For small and medium enterprises, borrowing conditions are particularly relevant, as many businesses depend on financing to purchase stock, equipment and other resources necessary for their operations.
E29 BILLION CIRCULATING IN BROAD MONEY SUPPLY
The Central Bank also reported that broad money supply, commonly referred to as M2, increased to E29 billion in August 2026.
This represents growth of 1.6 per cent compared with July and a substantial 12.6 per cent increase compared with August 2025.
Broad money supply is an important measure of liquidity within an economy.
It generally includes currency held by the public and certain deposits held with financial institutions, including funds that can be accessed or converted into spending power.
The increase to E29 billion indicates that the amount of money captured by this measure expanded during the reporting period.
For the banking sector, changes in money supply provide information about monetary conditions, deposit holdings and the availability of funds within the financial system.
For the wider economy, money supply developments are closely monitored because they can influence spending, saving, lending and investment.
However, an increase in broad money supply does not necessarily mean that households have become wealthier or that businesses are experiencing higher sales.
The distribution of money across households, companies and financial institutions, together with the prevailing economic conditions, determines how such changes affect economic activity.
The annual increase of 12.6 per cent is therefore a significant monetary development, but its wider implications must be considered alongside credit growth, inflation and other economic indicators.
DOMESTIC LIQUID ASSETS RISE TO E9.3 BILLION
The Central Bank’s figures further show that domestic liquid assets increased to E9.3 billion in August 2026.
This represents an 8.2 per cent increase from the previous month and growth of 3.8 per cent compared with August 2025.
Domestic liquid assets are an important component of the banking system because they represent assets that can be used or converted into funds to meet financial obligations.
A banking sector with adequate liquidity is generally better positioned to meet withdrawals, settle payments and manage short-term funding requirements.
The E9.3 billion figure therefore provides useful information about liquidity conditions within the domestic financial system.
The monthly increase of 8.2 per cent is particularly notable when compared with the 1.4 per cent decline in private sector credit over the same reporting period.
The two indicators measure different aspects of the financial system, but their movements show that increased liquidity did not coincide with an increase in outstanding private sector credit during August.
This distinction is important because the availability of liquid assets within the banking system does not automatically translate into increased lending.
Banks must consider borrower eligibility, credit risk, lending demand and regulatory requirements before extending financing.
For entrepreneurs seeking funding, the existence of liquidity in the financial system is therefore only one factor affecting access to credit.
BORROWERS FACE HIGHER INTEREST RATES
While the Central Bank reported increases in reserves, money supply and domestic liquidity, September also brought higher interest rates.
The Bank increased its discount rate by 25 basis points to 7.0 per cent, while the prime lending rate rose to 10.50 per cent.
A 25-basis-point increase is equivalent to 0.25 percentage points.
The discount rate is a key monetary policy rate that influences borrowing conditions within the financial system, while the prime lending rate serves as a reference rate for various loans offered by commercial banks.
The increase in the prime lending rate has implications for borrowers whose loan agreements are linked to changes in that rate.
For example, a business with a loan carrying a variable interest rate may face higher financing costs following an increase in the applicable lending rate.
Households with qualifying variable-rate loans may also experience changes in their interest payments or repayment arrangements, depending on the terms of their agreements.
To illustrate the potential effect, a 0.25-percentage-point increase on an outstanding loan balance of E100000 would amount to approximately E250 in additional annual interest, assuming the full increase is passed on and the balance remains unchanged.
For a business with an outstanding loan balance of E1 million, the equivalent increase would be approximately E2500 annually under the same assumptions.
Actual repayment changes depend on the type of loan, outstanding balance, interest calculation method and repayment period.
The increase in lending rates is therefore particularly relevant for businesses considering borrowing to expand their operations.
It also matters for households planning to finance homes, vehicles or other major purchases.
WHAT THE FIGURES MEAN FOR ESWATINI’S ECONOMY
Taken together, the Central Bank’s latest statistics provide several important indicators of the country’s monetary and financial conditions.
Foreign reserves increased to E10.8 billion, improving the country’s import cover to 2.5 months.
Broad money supply rose to E29 billion, while domestic liquid assets reached E9.3 billion.
Private sector credit stood at E23.5 billion, recording strong annual growth despite declining during August.
At the same time, the increase in the discount and prime lending rates means borrowers face higher reference interest rates than before September’s adjustment.
These developments are relevant to the government’s economic planning, the banking sector’s lending activities and the financial decisions made by businesses and households.
The figures also demonstrate why monetary indicators must be examined together rather than individually.
Higher money supply and increased banking liquidity do not automatically result in stronger private sector lending, just as higher foreign reserves do not necessarily mean that all external financial risks have been eliminated.
Similarly, the effect of higher interest rates depends on borrowing arrangements and the financial circumstances of individual businesses and households.
The Central Bank’s statistical release does not provide sufficient information to determine how these developments have affected employment, household incomes or business profitability.
Those outcomes would require additional economic data.
For now, the latest report shows an economy with improved foreign reserve holdings, expanding monetary aggregates and higher domestic liquidity, but also one in which private sector credit declined on a monthly basis and borrowing costs increased.
As Eswatini continues through the final quarter of 2026, subsequent Central Bank releases will provide further information on whether the improvement in reserves and liquidity is sustained, whether private sector credit recovers from its monthly contraction and how lending conditions develop following the September interest rate adjustment.
AT A GLANCE | CENTRAL BANK STATISTICS
| Economic indicator | Latest figure | Reported movement |
| Gross official reserves (September) | E10.8 billion | +2.6% monthly |
| Import cover (September) | 2.5 months | Up from 2.4 |
| Private sector credit (August) | E23.5 billion | −1.4% monthly |
| Broad money supply (August) | E29.0 billion | +1.6% monthly |
| Domestic liquid assets (August) | E9.3 billion | +8.2% monthly |
| Discount rate (September) | 7.00% | +0.25 percentage points |
| Prime lending rate (September) | 10.50% | +0.25 percentage points |
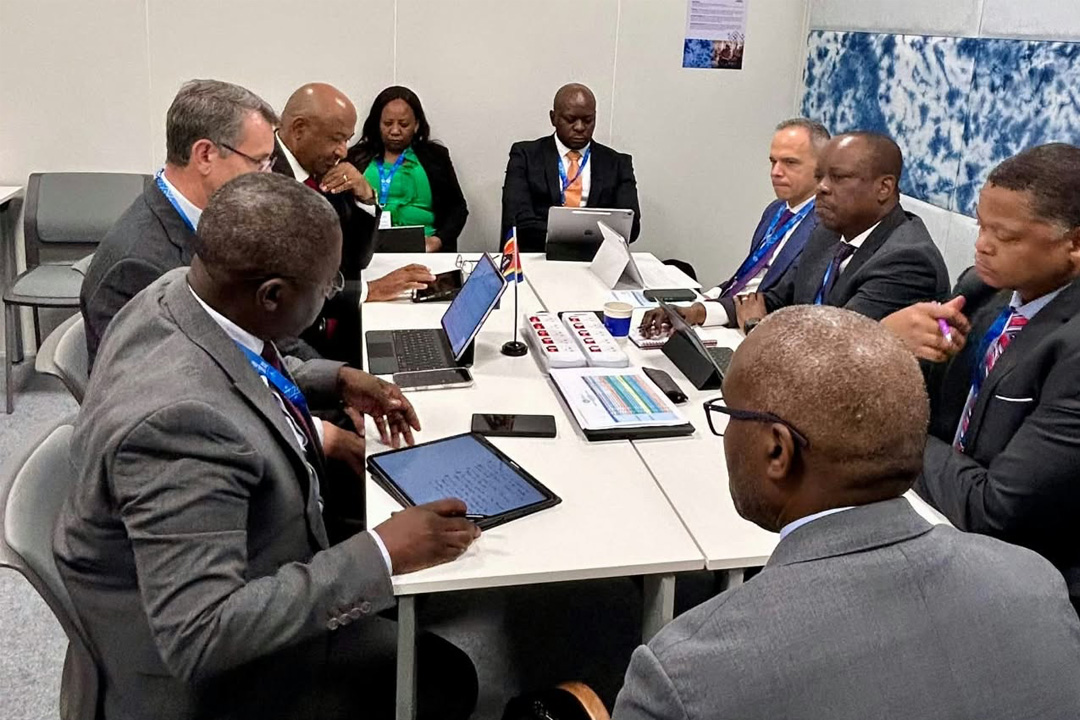
(Courtesy Pic)