
BY PHUMELELE GAMEDZE
MBABANE – The E10 billion owed by households and non-profit institutions is painting a worrying picture of the financial pressure confronting many emaSwati, with economist Sanele Sibiya warning that a growing shift towards unsecured borrowing suggests families are increasingly turning to loans to cushion themselves against the rising cost of everyday life.
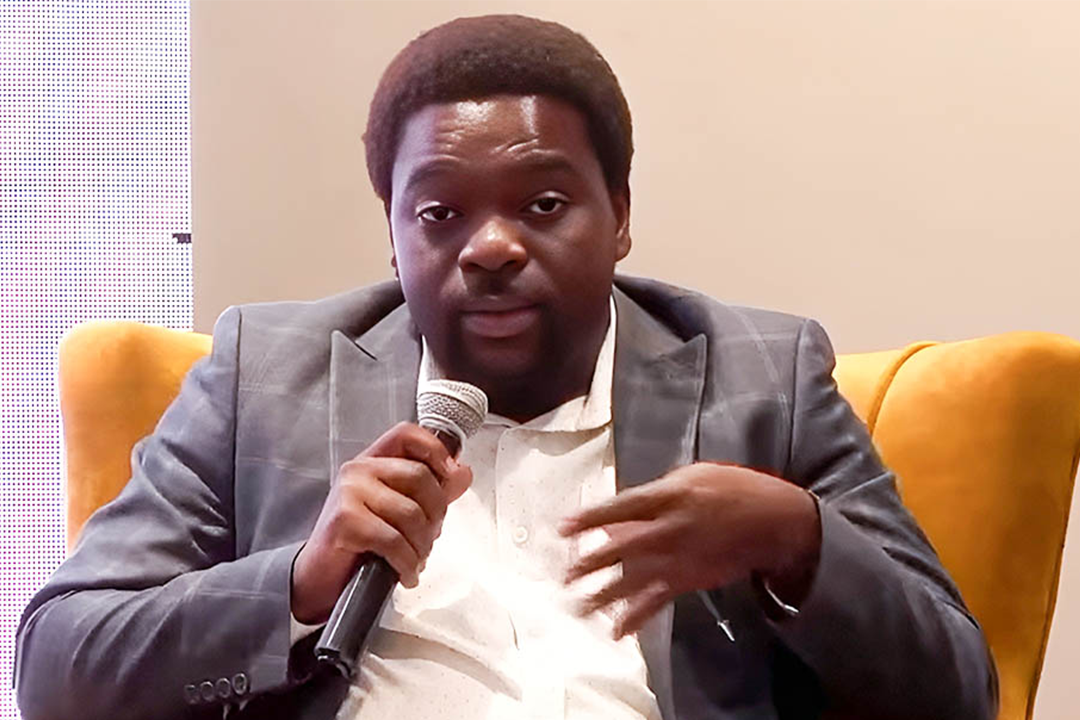
Sibiya made the observation during Eswatini TV’s Market View, where he was analysing the Central Bank of Eswatini’s latest monetary policy decision to raise the discount rate from 6.75 per cent to 7 per cent.
According to figures cited from the Central Bank of Eswatini (CBE), private sector credit reached E23.8 billion in July 2026, an increase of 11.4 per cent compared with the same period last year.
Households and non-profit institutions accounted for E10 billion of that credit, while businesses accounted for E12.9 billion.
For Sibiya, however, the more revealing issue is not simply how much people are borrowing, but the type of credit they are increasingly using.
He said secured lending, including mortgages, appeared to be declining while unsecured credit such as personal loans was rising.
That pattern, he said, could indicate that households are not necessarily borrowing to acquire long-term assets, but are increasingly looking for financial breathing space as everyday expenses eat into their incomes.
“It’s still painting the story of a household sector that is dealing with huge cost-of-living pressure,” Sibiya said during the programme.
The pressure could become even more pronounced for families already servicing loans following the latest increase in interest rates.
The CBE expects the prime lending rate to rise to 10.50 per cent. Borrowers whose loans are linked to the prime rate could therefore see their monthly repayments increase.
For households operating on already stretched budgets, even a modest rise in monthly loan instalments can leave less money available for essentials such as food, transport, school expenses and utilities.
Sibiya said the higher cost of borrowing would not affect households alone.
Small and medium enterprises could also feel the impact as financing becomes more expensive, potentially increasing the cost of borrowing for expansion, equipment purchases and other business investment.
There is, however, another side to the higher-interest-rate environment.
Sibiya noted that savers may benefit as financial institutions adjust their deposit and investment rates upwards, potentially offering better returns to people who have money set aside.
There are also positive developments on inflation.
The CBE has revised its 2026 inflation forecast down to 2.52 per cent from an earlier projection of 3 per cent. Its inflation forecasts for 2027 and 2028 were also revised to 3.86 per cent and 3.45 per cent respectively.
Inflation stood at 2.8 per cent in August 2026.
The wider economy has also remained resilient, recording year-on-year growth of 6.1 per cent in the first quarter of 2026, while the Central Bank is projecting full-year economic growth of 5.3 per cent.
Those figures present a mixed economic picture for households.
While inflation remains relatively contained and overall economic activity is positive, the growing use of unsecured credit suggests that a number of families may still be struggling to make their incomes stretch far enough.
Sibiya said disposable income remained a crucial concern.
As borrowing costs rise, households servicing loans could find themselves with even less money after monthly repayments, sharpening the pressure on family budgets.
The latest credit figures therefore go beyond a simple measure of banking activity. They provide an insight into how ordinary emaSwati are responding to economic pressures in their homes.
For households relying increasingly on personal loans, the concern is that credit may be moving from being a tool for investment towards becoming a buffer against everyday financial strain.
At the same time, lower inflation and continued economic growth offer some encouraging signs for the broader economy.
The challenge for households will be whether those positive indicators eventually translate into stronger disposable incomes and reduced dependence on borrowing to meet day-to-day needs.